TL;DR

Get the little things that make your day delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
A LifeHack report argues that downsizing in retirement does not automatically improve a household’s finances: sale, purchase and moving costs can absorb much of the price difference. It recommends estimating the move’s full cost and comparing it with realistic annual housing savings before deciding. The cited figures are broad estimates, and an individual outcome depends on actual properties, fees and circumstances.
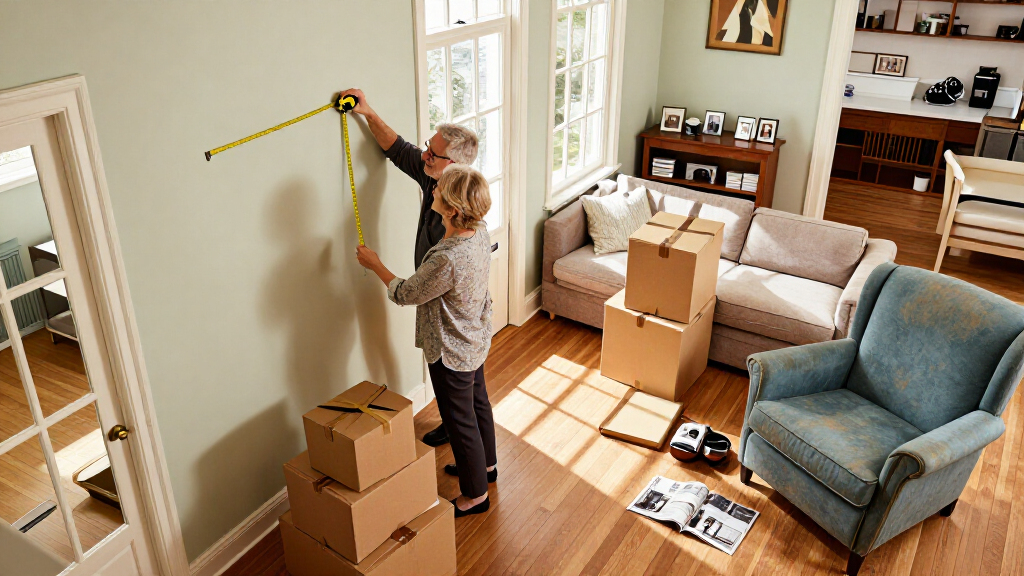
A LifeHack report on retirement downsizing says homeowners should calculate the full cost of selling, buying and moving—and how long any savings would take to repay it—before putting a home on the market. The report frames downsizing as a spending decision with a break-even period, not an automatic way to release usable cash.
The report says a lower purchase price does not equal the amount a seller keeps. It cites Freddie Mac guidance estimating seller fees and taxes at 2% to 4% of the sale price, in addition to agent commission, which the guidance gives as a broad 3% to 8% range. Freddie Mac’s cited estimate for buyer closing costs is 2% to 5% of the purchase price. These are budgeting ranges, not quotes for a particular transaction.
Moving adds another cost. The report cites Move.org estimates of about $7,600 for a full-service local move of less than 100 miles and $9,140 or more for a longer move. Actual prices depend on factors such as distance, home size and timing. The report also lists possible expenses after arrival, including replacement furniture, window coverings, storage fittings and repairs.
As an illustration, it compares selling a $450,000 home and buying one for $300,000, a $150,000 difference in listed prices. Based on the cited fee ranges, the report estimates that transaction costs could take about $28,500 to $69,000 before moving expenses or other setup costs. The illustration is not a personalized estimate; commissions and other charges vary.
The Move Must Earn Back Its Cost
The central financial question is not simply whether a new home costs less. It is whether the annual reduction in housing expenses is large enough to repay the one-time costs within a period that makes sense for the household. If the savings are modest, substantial fees can mean the owner waits many years to reach break-even—or does not reach it during the time they live in the new home.
That calculation matters because the decision can affect both retirement savings and day-to-day life. A sale may provide cash, but that cash is reduced by transaction and moving expenses. The report also notes that a home’s value cannot be assessed solely through its monthly bills: location, nearby services, family connections and the suitability of the home for changing mobility needs may all matter, though they are not captured in a break-even formula.
Those trade-offs cut both ways. Staying can mean continuing to pay for maintenance, taxes and insurance, while moving may reduce some costs but introduce new ones, such as a condominium or homeowners’ association fee. The report’s method is a way to compare scenarios, not proof that staying or moving is better for every retiree.
As an affiliate, we earn on qualifying purchases.
Costs Behind the Price Difference
The report cites an AARP 2024 Home and Community Preferences survey, which found that 75% of adults aged 50 and older said they want to remain in their current home as long as possible. That figure describes stated preference; it does not establish that all respondents can stay or that staying is financially preferable. It does, however, show why advice to move may not match what many older adults say they want.
Mortgage status can change the calculation. According to the report’s account of Harvard’s Joint Center for Housing Studies publication Housing America’s Older Adults 2023, in 2022, 41% of homeowners aged 65 to 79 had a mortgage, as did 31% of homeowners aged 80 and older. The report notes that homeowners without a mortgage still pay property taxes, insurance, utilities and upkeep. A smaller home may lower some of those bills, but it may also bring fees or different maintenance costs.
The report also cautions against assuming a standard agent commission. It says the National Association of Realtors’ practice changes took effect in August 2024: covered listing services may no longer display offers of buyer-agent compensation, and buyers working with an agent generally sign a written agreement setting compensation before touring homes. Sellers may still agree to cover some or all of that compensation. Homeowners should use the terms that apply to their own transaction rather than rely on a presumed national rate.
“The break-even is one division problem and it fits on a single sheet of paper.”
— LifeHack report
home sale transaction fee calculator
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Your Own Savings Remain Unknown
The cited percentages and moving figures are general estimates, not a quote for any reader’s sale or purchase. The source material does not provide a specific homeowner’s sale price, agent agreement, tax situation, moving distance, new-home expenses or expected annual savings. Without those details, no reliable break-even period can be calculated.
It is also unclear from the report’s example how much the hypothetical homeowner would save each year. That depends on the actual costs of both properties, including taxes, insurance, utilities, maintenance and any association fees. Repairs, accessibility work and the value of remaining near family or familiar services may also affect a person’s decision, but are not assigned dollar values in the example.
As an affiliate, we earn on qualifying purchases.
Price Both Homes Before Listing
The report recommends writing down every one-time cost, including selling and buying expenses, the mover’s quote and likely setup or repair spending. Then estimate the new home’s annual housing costs and compare them with the current home’s costs. Dividing the total one-time expense by annual savings gives an estimated number of years to break even.
Before making a decision, homeowners can replace the report’s broad ranges with written estimates and the actual compensation terms in any agent agreement. They can also compare the financial result with practical needs, such as stairs, upkeep, access to services and desired proximity to family. The report offers a calculation framework, but it does not supply a universal threshold for when a move is worthwhile.
As an affiliate, we earn on qualifying purchases.
Key Questions
What does the report mean by a break-even period?
It is the estimated time required for annual savings in housing costs to repay the one-time costs of selling, buying and moving. The report’s formula is total move costs divided by annual savings.
Does selling a home for more than the next home’s price mean I keep the full difference?
No. The price difference can be reduced by sale expenses, agent compensation, buyer closing costs, moving charges and costs of setting up or repairing the new home. Actual amounts depend on the transaction.
How long does it take to break even?
The report does not give a universal timeline. It depends on the homeowner’s total moving costs and the annual difference between the two homes’ ongoing expenses.
Is downsizing financially wrong for retirees?
The report does not establish that. It argues that downsizing can make sense in some cases, but should be judged using specific costs and expected savings rather than assumed to be a financial gain.
Source: rss
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.